Financial literacy is an essential life skill that empowers individuals to navigate their economic environment confidently. For pre-teens (typically ages 9-13), cultivating strong financial habits can set the stage for lifelong competence in managing money, making informed decisions, and avoiding common financial pitfalls. This guide explores comprehensive routines and strategies for building financial literacy in pre-teens, integrating evidence-based practices and actionable steps for families and educators.
Why Financial Literacy Matters for Pre-Teens
Developing financial literacy in pre-teens lays a crucial foundation for adulthood. Research shows that children and young teens who receive early financial education are more likely to budget effectively, save consistently, and avoid debt in the future. Without deliberate instruction, pre-teens risk entering adulthood lacking essential knowledge in budgeting, saving, credit, and long-term planning.
- Future preparedness: Today’s complex economic environment demands early competence in money management.
- Limited formal education: Only a minority of states require personal finance education, leaving gaps in formal schooling.
- Formative years: Habits and attitudes toward money solidify during pre-adolescence, shaping later behavior.
Core Money Concepts for Pre-Teens
Teaching pre-teens about money should cover a spectrum of foundational topics. Key areas of focus include:
- Budgeting: Understanding how to plan, track, and manage income and expenses.
- Needs vs wants: Differentiating between essential and discretionary spending.
- Earning: Recognizing the value of work and the connection between effort and money.
- Savings: Setting goals and creating plans to achieve them.
- Giving: Developing attitudes of generosity and social responsibility.
- Smart spending: Learning to compare prices, avoid unnecessary purchases, and mitigate the impact of marketing.
Building Financial Literacy Through Daily Routines
Integrating financial lessons into everyday activities creates organic, memorable learning opportunities. Families and educators can instill financial literacy by establishing predictable routines and involving pre-teens in real-life money decisions.
Everyday Routines for Financial Literacy
- Including children in grocery shopping and budgeting discussions
- Assigning regular chores tied to earning an allowance
- Tracking family expenses together and discussing trade-offs
- Reviewing receipts, bank statements, or digital transaction history
- Setting weekly or monthly money meetings to check on goals and spending
- Encouraging children to research and compare products before purchases
Budgeting and Allowance Systems
One of the most effective ways to teach pre-teens about money is through hands-on budgeting using an allowance. A structured allowance system supports budgeting concepts, encourages prudent spending, and helps kids experience the consequences of their choices.
Implementing an Allowance Routine
| Allowance Practice | Description | Financial Skill Developed |
|---|---|---|
| Bi-weekly Allowance | Give a set amount every two weeks rather than weekly to promote planning. | Budgeting, Delayed Gratification |
| Earning Allowance | Tie allowance to completion of household chores or small jobs. | Work Ethic, Earning |
| Three Envelope System | Divide allowance into buckets: Save, Spend, Give. | Saving, Spending, Philanthropy |
| Use of Apps | Leverage child-friendly financial apps for digital tracking. | Digital Money Skills |
Encouraging pre-teens to allocate portions of their allowance for different purposes reinforces the concept of opportunity cost and purposeful spending.
Needs vs Wants: Understanding Spending
A core financial lesson is distinguishing between needs (essentials like food, shelter, clothing) and wants (non-essential, discretionary items). Teaching this concept early prevents impulsive spending and fosters intentionality.
- Discuss family budgets openly, highlighting essential expenditures.
- When considering new purchases, encourage children to ask: Is this a need or a want?
- Involve them in prioritizing spending within given limits.
- If a pre-teen desires a premium item, consider requiring them to pay the difference with their own money.
Earning and Working Experiences
Allowing pre-teens to earn money through age-appropriate work promotes an appreciation for the value of labor and helps them link effort to financial reward.
- Encourage participation in neighborhood jobs (e.g., pet sitting, yard work).
- Set up micro-business opportunities, like selling handmade crafts or organizing a garage sale.
- Discuss the time, planning, and effort involved in earning money beyond allowances.
Such experiences deepen empathy for working adults and foster a proactive financial mindset.
Long-Term Goals and Saving Habits
Goal-setting is a powerful motivator for saving. Help pre-teens establish both short- and long-term financial goals, breaking them into manageable steps. Use visual aids like goal charts or savings trackers to monitor progress.
- Identify something meaningful they want to save for (e.g., a gaming device, trip, or special event).
- Calculate how much needs to be saved and map out a plan over weeks or months.
- Celebrate milestones to reinforce positive saving behavior.
- Introduce the concept of interest: show how money can grow in a savings account over time.
Spending Strategies and Smart Consumer Behavior
Pre-teens are increasingly exposed to aggressive marketing and peer influence. Equip them with skills to resist impulsive purchases and become informed consumers.
- Discuss the role of advertising and branding in shaping preferences and spending.
- Practice comparison shopping for major or frequent purchases.
- Talk about responsibilities and possible consequences when using money for entertainment, digital apps, and in-game purchases.
- Discuss delaying purchases to encourage thoughtful decision-making.
- Encourage proactive seeking of sales, discounts, and evaluating value for money.
Teaching Through Technology and Games
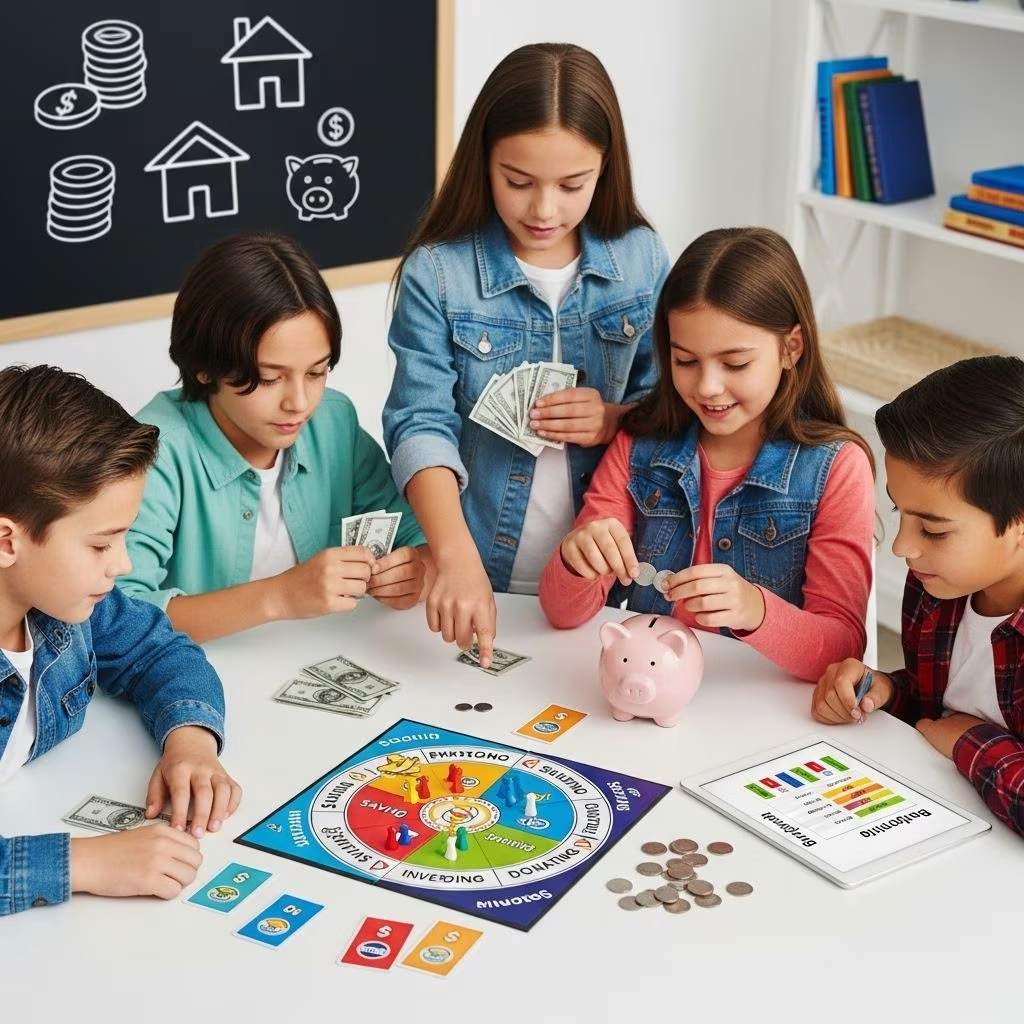
Multiple educational platforms offer interactive and engaging ways for pre-teens to learn financial skills. Digital programs, games, and apps simulate real-life scenarios and encourage applied learning[10].
- Use online courses like MoneyTime, which covers core money concepts via self-directed lessons for ages 10-14.
- Explore educational games such as FDIC’s Money Smart for Young People, Visa’s Financial Football, or Banzai’s life skills simulations[10].
- Implement financial apps that track allowance, savings, goals, and expenses in a kid-friendly format.
Technology enhances learning by making concepts interactive and relevant to digital-native pre-teens.
Family Involvement and Modeling Behavior
Adults are the primary source of financial learning for many pre-teens. Modeling healthy financial behaviors—such as budgeting, delayed gratification, responsible credit use, and charitable giving—imprints enduring lessons.
- Hold regular family discussions about money goals, saving for vacations, or upcoming purchases.
- Explain family financial decisions in age-appropriate terms.
- Demonstrate charitable giving and involve pre-teens in choosing causes to support.
- Share personal stories of financial mistakes and lessons learned.
- Encourage transparency in discussing challenges as well as successes.
Educational Resources and Curricula
Numerous free and paid resources are designed for parents, homeschoolers, and teachers aiming to implement robust financial literacy routines in pre-teens’ lives.
- ChooseFI PreK-12 Curriculum: Free, adaptable lesson plans for all grade levels.
- MoneyTime: Self-directed digital lessons and activities tailored for kids ages 10-14.
- Money Smart for Young People: FDIC’s curricula with age-specific guides, activities, and real-life examples.
- Junior Achievement’s Finance Park: Simulation-based learning for grades 6-9 on money management and career planning.
- Banzai: Interactive modules and real-world scenarios for grades 3-12[10].
- Practical Money Skills and Better Money Habits: Printable worksheets and games for individual or group learning.
- Khan Academy Financial Literacy: Free online courses covering budgeting, saving, credit, insurance, and taxes.
Integrating these resources with daily routines provides a holistic approach to building financial literacy.
Frequently Asked Questions (FAQs)
Q: How much allowance is appropriate for pre-teens?
A: The amount is less important than the purpose. Allowance should fit the family budget, cover agreed responsibilities, and allow enough for pre-teens to budget for saving, spending, and giving. Adjust as children demonstrate maturity and responsibility.
Q: What’s the best age to start teaching financial literacy?
A: Start as early as possible—simple concepts for younger children and more complex lessons for pre-teens. Consistency and hands-on involvement over several years are key.
Q: How can I make financial topics engaging for my pre-teen?
A: Use real-life scenarios, gamified learning platforms, goal-setting challenges, and involve them in financial decisions relevant to their interests (e.g., saving for a desired item or planning a family event budget).
Q: Should pre-teens have their own bank account?
A: Having a supervised savings or checking account can teach practical banking skills and accountability. Many banks offer child-friendly options with parental controls.
Q: How do I address peer pressure and marketing influences?
A: Talk openly about branding, advertising tricks, and the difference between personal values and social pressures. Practice responding to peer-driven requests with reasoned, value-based decision-making.
Conclusion
Financial literacy is a continuous journey, not a one-time lesson. Through purposeful routines, supportive family involvement, and access to high-quality educational resources, you can empower pre-teens to make wise financial choices and build a foundation for lasting success. Start today and help them discover the value of money, the importance of planning, and the rewards of financial independence.
References
- https://www.choosefifoundation.org/prek12
- https://www.kidsfinancialeducation.com/advice/ages-11-13/
- https://ospi.k12.wa.us/student-success/resources-subject-area/financial-education/financial-education-resources
- https://www.moneytimekids.com
- https://utahparentcenter.org/financial-lit/
- https://www.fdic.gov/consumer-resource-center/money-smart-young-people
- https://www.cde.ca.gov/eo/in/fl/finlitk12.asp
- https://www.khanacademy.org/college-careers-more/financial-literacy
- https://www.consumerfinance.gov/consumer-tools/educator-tools/youth-financial-education/
- https://banzai.org